Blog · Part of the Money and Tax guide
OnlyFans Financial Planning: Saving, Tax and Investing
Financial planning for OnlyFans creators, in order: build an emergency fund, set money aside for tax, then invest, and keep lifestyle creep in check.
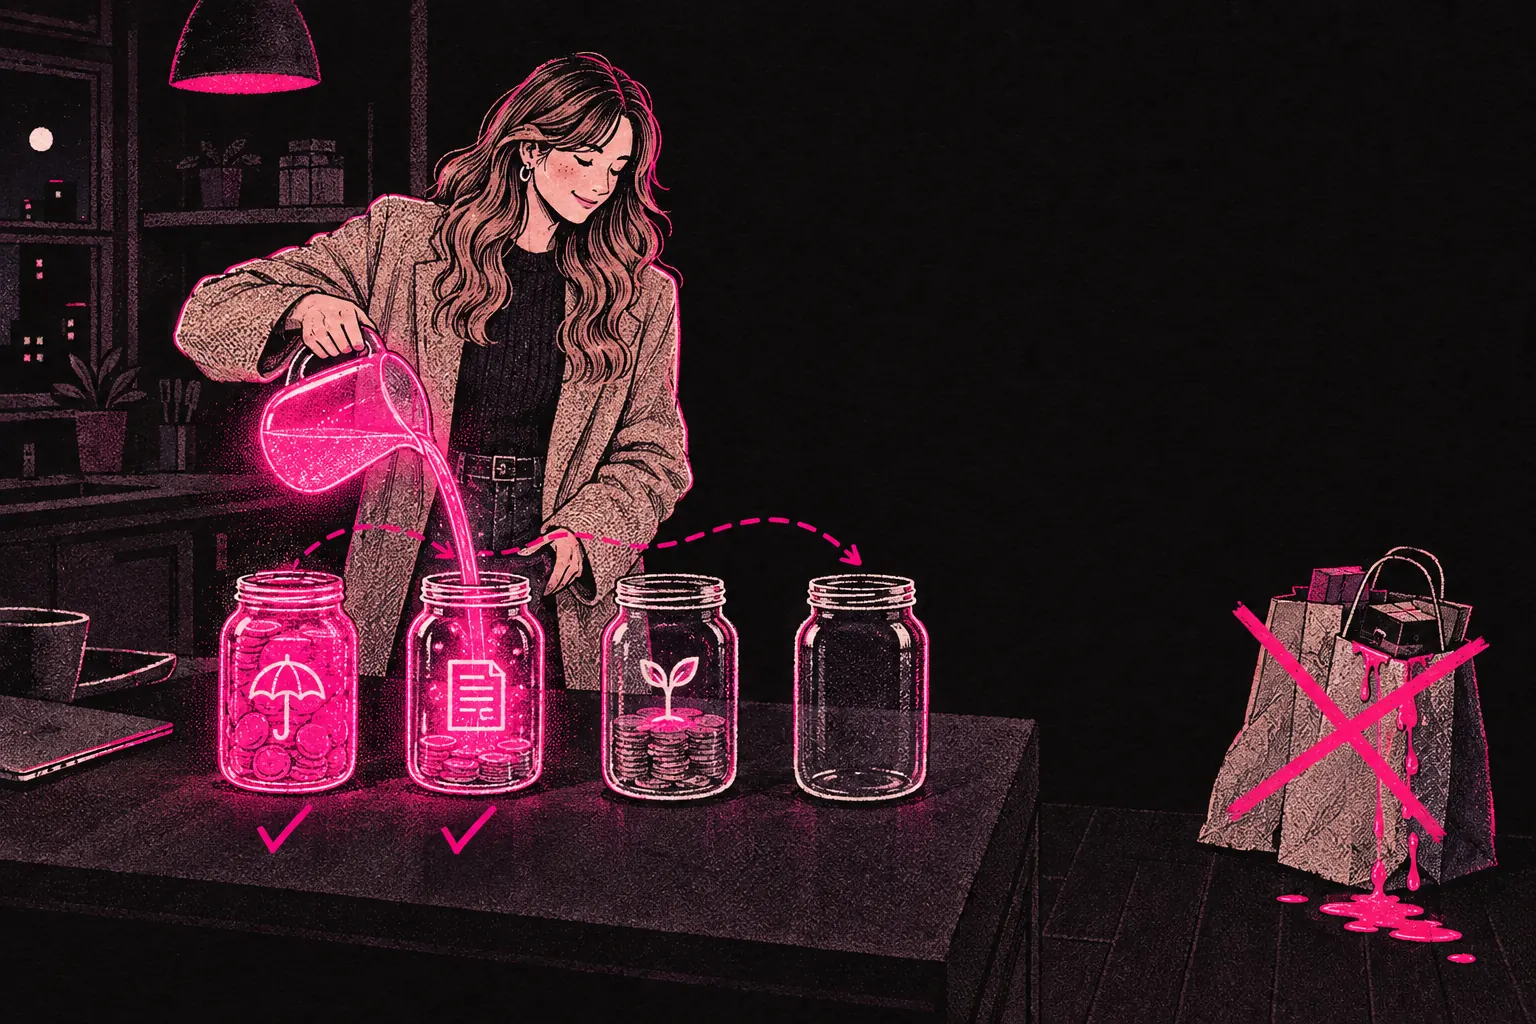
Financial planning as an OnlyFans creator comes down to four things, in this order: build an emergency fund, set money aside for tax as you earn it, invest once both are covered, and keep your spending from rising every time your income does. That order works when you’re earning your first few hundred pounds, and it still works when you’re earning a lot more.
If you’ve ever watched a great month disappear into bills, subscriptions and impulse buys with nothing left over, you’re not bad with money. You’re running a business with an income that changes every month, without a system built for that. Setting one up isn’t complicated once you know the basics.
Why Financial Planning Matters More for Creators
Most money advice assumes a steady monthly salary. You don’t have one. Creator income goes up and down with the seasons, how much you post, how many subscribers you lose and changes to platform algorithms. One month might be excellent, and the next might drop a long way.
That makes planning harder, and it also makes it more important. Without a system, you’ll always feel like you’re reacting to money instead of steering it. A proper plan gives you:
- The confidence to put money into your business (equipment, marketing, collaborations)
- Protection against slow months, without the panic
- A clear route towards long-term goals beyond content creation
- Less money worry, which affects your mental health and your creative work
Building an Emergency Fund First
Before you think about investing or big purchases, you need a buffer. With an income that changes month to month, the usual advice of three months’ expenses isn’t quite enough. Aim for four to six months of your basic living costs, kept in an easy-access savings account.
Basic costs means rent, utilities, food, transport and any debt repayments. Subscriptions, nights out and new equipment don’t count.
To build it:
- Work out your baseline. Add up the monthly costs you can’t avoid, then multiply by five. That’s your target.
- Automate a percentage. Every time you get a payout, move a fixed share (20 to 30%) into a separate savings account before you spend anything else.
- Use our earnings tool. Track your income with our earnings calculator so you can see your average month and plan around that, instead of around your best one.
- Leave it alone. This fund is only for real emergencies. A slow month isn’t an emergency if you’ve planned for it. A broken laptop or a surprise bill is.
With the fund in place, a quiet month is far less frightening, and it’s much easier to make good decisions about your content when next month’s rent is covered.
Tax Planning: The Non-Negotiable
Money you earn from OnlyFans in the UK is taxable, and HMRC expects to hear about it. Getting it wrong creates problems that get bigger the longer you leave them.
The basics:
- Depending on how much you earn, you’ll need to register as self-employed or run your earnings through a limited company. GOV.UK explains when you have to register.
- Once you’re registered, you file a Self Assessment tax return every year.
- As a sole trader, you pay Income Tax plus Class 4 National Insurance, which is 6% on profits from £12,570 to £50,270, then 2%. Class 2 is no longer compulsory, and for 2026/27 it’s credited automatically if your profits are £7,105 or more. Below that, you can pay it voluntarily at £3.65 a week.
- Set aside part of every payout for your tax bill as you earn it. Our tax calculator will estimate how much, and you can check the current Income Tax rates on GOV.UK.
- You can lower your tax bill by claiming allowable business expenses.
We’ve written a lot about this. Start with our complete UK tax guide, then read the Self-Assessment walkthrough. If you’re not sure whether to register as a sole trader or set up a limited company, our comparison guide sets out the pros and cons at different income levels.
Claim everything you’re entitled to. Equipment, internet costs, a share of your home costs if you work from home, software subscriptions and more can all reduce your tax bill. Our expenses guide lists what qualifies.
Check the tax calculator at any point in the year to see roughly what you owe, so January doesn’t bring any surprises.
Investing as a Creator
Once your emergency fund is in place and your tax is covered, you can start investing for the long term. You don’t need to be a finance expert to start.
To keep it simple at the start:
- A Stocks and Shares ISA lets you invest tax-free, up to £20,000 a year across all your ISAs. Check GOV.UK for the current allowance.
- Index funds (which track the overall stock market) are low-cost and don’t need much knowledge.
- Investing small amounts regularly gives compound growth time to work.
- You don’t need to time the market. Investing regularly matters more than picking the right moment.
What to avoid:
- Don’t invest money you might need in the next three to five years.
- Avoid picking individual shares unless you properly understand the company.
- Be extremely wary of crypto, forex schemes or anyone promising guaranteed returns.
- Never invest your emergency fund or your tax money.
If you’re balancing OnlyFans with a day job, you may already have a workplace pension. Check whether your employer matches your contributions, because that’s close to free money.
Planning for the Long Term
Content creation, like any career, has phases. What you can earn on the platform may change over time, and that’s fine as long as you plan for it.
Long-term planning means thinking about:
- Pension contributions. As a self-employed creator, nobody auto-enrols you into a workplace pension, so you’ll need to set one up yourself. A SIPP (Self-Invested Personal Pension) gives you tax relief on contributions and lets you choose your own investments.
- Diversifying income. Could you earn from things beyond the platform? Merchandise, coaching, digital products or other projects can make you less dependent on one source.
- Exit planning. Whether you create content for two years or twenty, a plan for moving on matters. Our exit strategy guide covers how to think about it without pressure.
- Skills and qualifications. Courses or qualifications give you options, whatever happens with the platform.
A success-oriented mindset means thinking beyond this month, or even this year. Treat your page as a business with a timeline, and plan for the day it changes.
Avoiding Lifestyle Creep
Lifestyle creep is when your spending rises in step with your income. You earn more, so you spend more, and your savings stay flat or even shrink. It’s an easy trap to fall into after a spell of fast growth.
Signs it might be happening to you:
- Your list of “essentials” keeps growing to include things that were treats six months ago
- You can’t say how much you saved last month without checking
- A dip in income would stress you out straight away, because your spending has risen to match your best months
- You justify spending because “I deserve it after working so hard”
You do deserve nice things. You also deserve financial security, and with a system in place you can have both.
To keep it in check:
- Pay yourself a fixed “salary” from your creator income, however much you earn that month. Save or invest the rest.
- Wait 48 hours before any purchase over £100. If you still want it after two days, buy it.
- Review your subscriptions every quarter. Cancel anything you haven’t used in the past month.
- Keep healthy boundaries between work and spending. Constantly rewarding yourself for working hard can become a cycle that’s hard to break.
Where to Start This Month
Good financial planning gives you choices: how long you create for, what you invest in, when you take breaks and what your life looks like in five or ten years.
Start with the emergency fund. Then sort out your tax. Build from there. You don’t have to do everything at once, but do start.
If you want help understanding your numbers, our tax calculator and earnings tool are free to use.